Tourlite @_Tourlite
Investment Manager - founded by @jeffreycherkin --- Disclaimer: Not investment advice. Opinions are our own. Retweets are not endorsements. tourlitecapital.com New York, NY Joined January 2022-
Tweets80
-
Followers1K
-
Following1
-
Likes16
$FTAI added as a new "Best Idea Long" by @HedgeyeIndstrls. Jay consistently does great work. Looking forward to reading the full report! Long FTAI: Van Sciver is presenting New Best Idea Long (FTAI) Thursday, September 3rd @ 2pmEST. FTAI is perhaps one of the more contentious names in Industrials. Jay has been pitched it as a long and as a short. Investors no doubt suffer a bit of ‘brain damage’ to understand the business model and complexities. Jay has come to think much of that skepticism stems from missing the broader picture of a business with several higher-return investment options…along with management’s inconsistent communication. Over time, FTAI has grown well and executed within a favorable niche in aerospace (+ energy). For investors, the transition to a leading independent platform in the engine leasing and MRO market with opportunistic moves beyond the core aviation platform, should be rewarding. Van Sciver thinks shares of FTAI offer 30%+ upside from current levels, with the recent down move getting us off the fence. FTAI certainly isn’t perfect, and we recognize that the upside is better appreciated than it was a few years ago. Engine platform dependence, tie-ins with the data center build-out narratives (sum-of-the-parts framework), and moves outside of core markets all present some risks. @Hedgeye @KeithMcCullough
$BODI trading at <2x Ebitda with net cash. Growing the @P90X @shakeology supplement brands. Private equity has been buying supplement companies at 3-6x revenue That would put Shakeology's valuation alone at $200-$300m vs $BODI market cap of $50m @P90X launched in retail this year and has been expanding in more $SFM locations and recently launched in @VitaminShoppe
Using @FundaAI assumptions, $FTAI Power could generate $1-1.3bn of Ebitda next year on 100 units and 2027 estimates are way too low (guidance of $450m). According to @FundaAI, FTAI's recent $1.465bn power deal to $SPCX is for 1GW. That means it's only 40 units and it implies a $36.6m per unit sale price vs original comments of $25m ($1m/mw). If margins are 30-35%, Ebitda per unit could be $10-13m... x100 = $1-1.3bn.
FTAI Announces $1.465 Billion Gas Turbine Generator Set Order Through J&F Power Systems ir.ftaiaviation.com/news-releases/…
$FTAI Power JV partner: Yantai Jereh Oilfield’s Unit Wins $1.47 Billion Power Order FTAI Power business is real and the stock does not reflect the reality $Meta $Googl $amzn $msft $spcx

$FTAI Power JV partner: Yantai Jereh Oilfield’s Unit Wins $1.47 Billion Power Order FTAI Power business is real and the stock does not reflect the reality $Meta $Googl $amzn $msft $spcx
$FTAI Power is basically the only guy on the block with 2027 capacity. 100+ engines = 2.5GW+ of 2027 capacity $GOOGL $META $SPCX all need power for their promised 2027 capacity @zerohedge

Josh Sullivan, early bull on $FTAI <$20, believes FTAI Power has a longer runway than many assume with tailwinds from AI/data center build outs. FTAI 25mw Mod-1 is a flexible power options which can be transported and used as a way to increase capacity at an existing facility


Jones analyst Josh Sullivan's $FTAI note this morning is the most realistic 2027 EBITDA estimate from the sell side. Josh's $2.9bn is 30% above cons $2.2bn $FTAI currently trading at 8x Josh's 2027 EBITDA

Jones analyst Josh Sullivan's $FTAI note this morning is the most realistic 2027 EBITDA estimate from the sell side. Josh's $2.9bn is 30% above cons $2.2bn $FTAI currently trading at 8x Josh's 2027 EBITDA
$FTAI Power is basically the only guy on the block with 2027 capacity. 100+ engines = 2.5GW+ of 2027 capacity $GOOGL $META $SPCX all need power for their promised 2027 capacity @zerohedge
Today PJM failed to secure 7GW in energy to ensure system stability into 2028 (due to price caps, without which electricity prices would be 70% higher). PJM is already below the critical reliability threshold, and in 2027 is facing a catastrophic shortage of power and brownouts
After announcing FTAI Power in December and a $GE partnership this morning: what if $FTAI does $2.9B of EBITDA in 2027, compared to current consensus estimates of $1.8B? It is likely the stock would trade above $400
We continue to believe $FTAI is one of the most attractive asymmetric opportunities in the market. We believe the stock is worth over $250 within the next year and has multiple catalysts over the next two years
Estimates will likely continue to go higher from here $FTAI

CEO of $FTAI just used his entire $14 million lifetime gift exemption to transfer FTAI shares into a dynasty trust. For a Fortress partner likely with significant other assets, that says a lot about his confidence in the stock’s future appreciation sec.gov/Archives/edgar…
Interesting $FIP update from @_Tourlite, seeing multi-bagger potential. The market didn't take $FIP ’s August deal to acquire Wheeling & Lake Erie Railway well, mostly due to headline leverage and preferred-equity warrants, but this misses the long-term value creation. Many assets are still ramping, masking true earnings power. Management is signaling confidence through early option exercises. RailCo alone could be worth $10+ per share, Repauno another $12+, and Long Ridge $6–12 depending on a data-center agreement. Altogether, $FIP SOTP could exceed $15 per share as catalysts unfold over the next year.
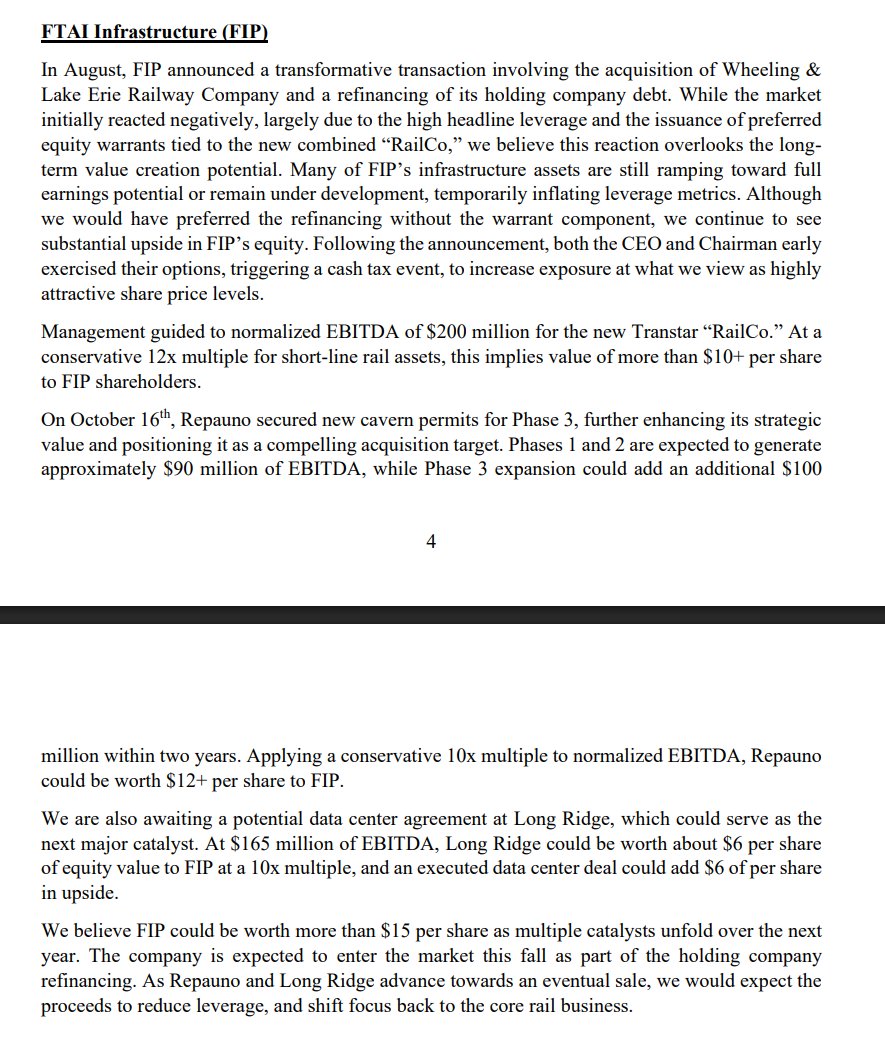
Big news for $FIP. The recently approved Phase 3 permits at Repauno could add $100M in EBITDA in 2 years. The asset would go from losing money to generating ~$190M EBITDA, making it potentially FIP’s most valuable asset

We continue to believe $FTAI is one of the most attractive asymmetric opportunities in the market. We believe the stock is worth over $250 within the next year and has multiple catalysts over the next two years
$FTAI call highlights: 1) FY25 EBITDA raised, 2) Upside momentum to FY26 assumptions, 3) 2H FCF "unspoken for" and could be looked at in regard for shareholder returns, 4) $4B Strategic Capital Initiative strategy off to the races,
CEO of $FTAI just used his entire $14 million lifetime gift exemption to transfer FTAI shares into a dynasty trust. For a Fortress partner likely with significant other assets, that says a lot about his confidence in the stock’s future appreciation sec.gov/Archives/edgar…
@HaydenCapital @LaughingH20Cap @gatorcapital @ArtkoCapital @SagaPartners 12) $FTAI by Tourlite Capital (+190%) FTAI Aviation was one of the more popular picks among small-cap funds this year and worked out for all of them

Congrats to $FTAI


$FTAI - Benchmark Raises to $300 PMA Approval for CFM-56 Part, Adds Rocket Fuel to High Flying Module Factory -This event marks a seismic shift in the multi-billion-dollar jet engine aftermarket industry and is the corner stone of FTAI’s long-term strategy -FTAI is gaining this
Nice analysis on $FIP! We have owned the stock since its spin off from $FTAI
$FIP 3Q Earnings call just ended **********THIS IS THE NEXT ONE - FOCUS************* 1 Year Target $18-20 2 Year Target $30-35 EBITDA up 7.5% to $36.9mm = $148mm Annualized Long Ridge - Utility 2Q EBITDA $11.1mm = $44mm Annualized -They said "We expect to sign a data center
$FTAI

$BA tumbling to a two-year low! @KahyaogluSheila of @Jefferies joins 'Fast Money' to explain why she reiterated her 'Buy' rating on the stock recently and why $FTAI might be giving the aerospace giant a run for its money:

#IQTooHigh @AnIQTooHigh
2 Followers 213 Following
Cam Mackintosh @RelativInvestor
116 Followers 1K Following Lefty. Make Something Wonderful. https://t.co/CPziaQgbOu
Casey @therealzuke
118 Followers 309 Following
Stock Thoughts @stockthoughts81
12K Followers 9K Following Public equity analyst and author of the Stock Thoughts newsletter.
Shiv Socrates @shivsocrates
1K Followers 7K Following Investing. Prev: Colossus 🎙️, NY Tech M&A, CPG sales; 📚 @Wharton. Less dumb than yesterday (hopefully). German shepherds for life.
Finman @qeinfinityy
30 Followers 1K Following
Disco Stu @stumvc007
1K Followers 3K Following Investment Viticulturist and wannabe reasonable golfer. Proprietor of the world's ugliest feet and worst beard.
MainSpring Research @MainspringETFs
139 Followers 893 Following Don’t believe everything you think. All ETFs are wrong, some are useful. Not Financial Advice.
1107 @08301107SP
17 Followers 176 Following
Doug @playmaker777
61 Followers 798 Following
Westminister Capital @WestministerCap
37 Followers 304 Following
Keith Zohan @KeithRosen11422
168 Followers 822 Following trying to find compassion and reason in a sea of online nonsense
SARB @WilliamJolyon
37 Followers 826 Following
Claudio @MonyaiTiego
19 Followers 2K Following
Roger Fritz @rogercfr
218 Followers 1K Following
SMR of GA @stevenmackr
238 Followers 1K Following
Adrian Garcia @adriangarcia174
460 Followers 4K Following South Texan, American, Engineer, Pseudo Intellectual and often wrong

Nesh @Dineshsrd
114 Followers 822 Following Primarily Invests in UK small/midcaps. Life long learning.Investing for 16+ years, Mistakes teach you more than successes, have fun along the way and respect .
Protest @protestcap
25 Followers 463 Following
Dovbear @Dovbear2166
4 Followers 49 Following
xxx @robertmusilQQQ
54 Followers 801 Following
L/S Analyst @Analyst1989
43 Followers 349 Following
Rodrigo Morfin @romorfinro
2 Followers 33 Following
U308xag @u308xag
112 Followers 3K Following
Dylan Joven @jovenator34
1 Followers 45 Following
KW @kw18720
0 Followers 19 Following
Sr. Chetis @DonChetis
2K Followers 3K Following Deporte, música y value investing | Long-term learner
Egehan Kıral @EgehanKirall
9K Followers 746 Following Boğaziçi - Ekonomi | Düzey 3 - Türev | #TMS Fon Yöneticisi. https://t.co/iWrvwVEfjv
Eric Thornton @ethorwut
21 Followers 290 Following
Amom @AmomAndrew520
124 Followers 2K Following
N_SAVANI @N_Savani_NY
164 Followers 3K Following Equity Derivatives-Elevated Volatility Portfolio Manager, Special Sit Investing & Liquidity/Asset Lending /RE Investor/Long Term Thinker, Short Term Investor
Sam Hollanders @SamHollanders
3K Followers 469 Following Fulltime belegger sinds 2010. Co-founder Chess Capital Fund. Gratis nieuwsbrief in je mailbox: https://t.co/GjT3HvMLE9
Michael Crowley @mcrowley128
54 Followers 343 Following
patrickcl @patrickcl15
30 Followers 296 Following
Carlos matos @Carflos223Matos
435 Followers 4K Following
Capvalue89 @CapitalOnValue
578 Followers 4K Following "On occasion, I have disobeyed orders." J. T. Kirk


Luis Castillo @lcastillod97
20 Followers 176 Following
L @victo16985
3 Followers 154 Following
Paco @PaquitoPF
1K Followers 8K Following
Dan Slipp @DanSlipp
53 Followers 947 Following
JT @JosephTalia
533 Followers 6K Following
GÖRDES @FrancJrG
120 Followers 512 Following University of Mannheim student, Management https://t.co/YKgbgfXBoG.
Broke Capital @broke_capital
109 Followers 2K Following Europoor shitco investor on the quest for correlated return-free risk
Jeff Cherkin @JeffreyCherkin
2K Followers 18 Following Investor @_Tourlite ··· Disclaimer: Not investment advice. Opinions are my own. Retweets are not endorsements.You might like